Can You Get a DSCR Loan on a Vacant Rental or a Brand-New ADU?
You did the work, got the permits, and the keys are in your hand. No tenant yet does not have to mean no loan.
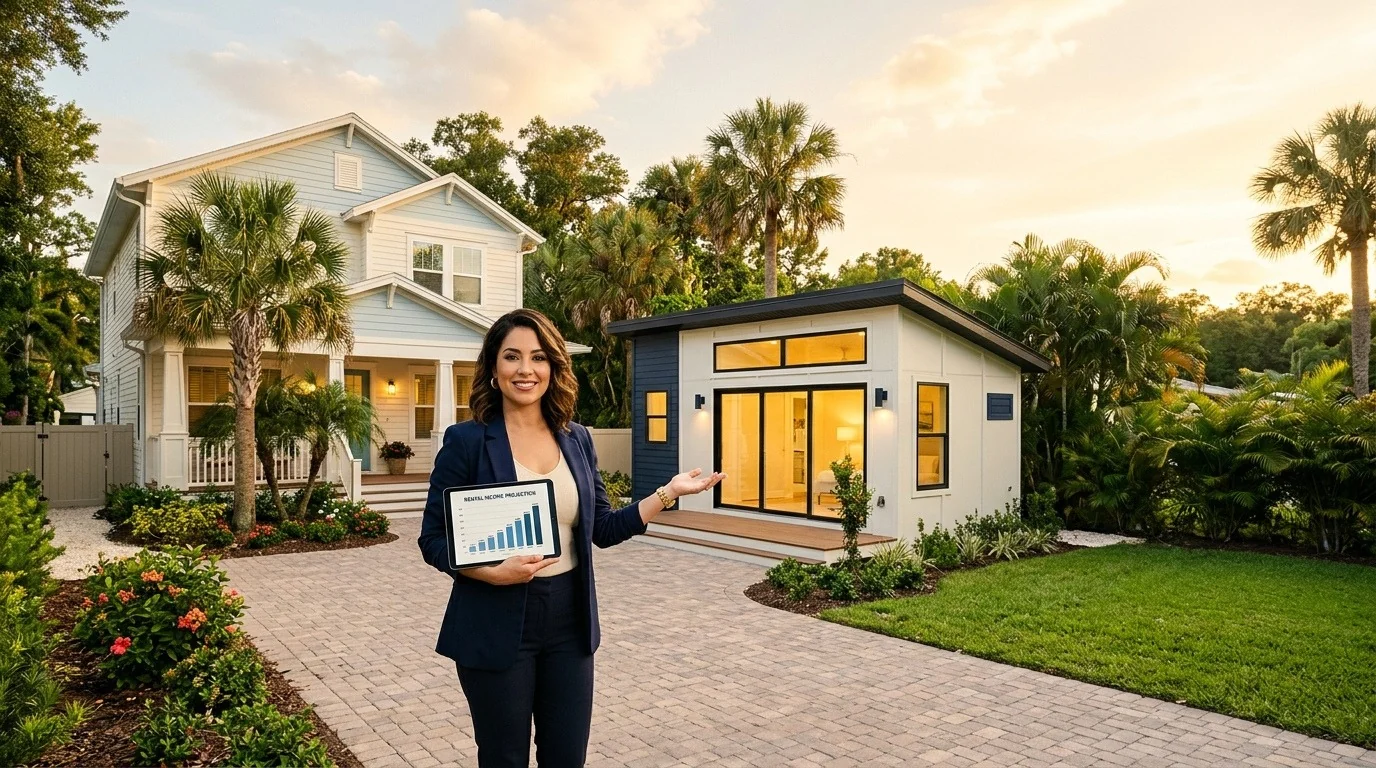
Picture this. You spent months on the addition. The inspector finally signed off, the certificate of occupancy landed in your inbox, and the new backyard unit looks like a magazine spread. Now you want to pull cash out or refinance, and the first question a lender asks is, “Who is living there?”
Nobody yet. And somehow that feels like you did something wrong.
You did not. Vacant, freshly improved properties are one of the most common stories I see from investors, and there are real programs built around them. The trick is knowing how lenders count rent when there is no lease, and what an ADU changes about the math.
Can I get a DSCR loan on a vacant rental with no tenant?
- Often yes. Many DSCR programs accept the appraiser’s market rent when there is no lease.
- DSCR means debt service coverage ratio: monthly rent divided by the monthly housing payment.
- Vacant refinances may carry lower maximum loan-to-value or seasoning rules than leased properties.
What is a DSCR loan? It is an investor mortgage that qualifies the property itself. Instead of tax returns and pay stubs, the lender asks one question: does this property’s rent cover its payment?
That is the benefit. For an investor with strong write-offs or a complicated income picture, the loan decision rides on the property, not on your personal return.
| Feature | What it means for you |
|---|---|
| Property rent drives qualification | No tax return write-off penalty on your personal income |
| Market rent from the appraisal | A signed lease is not always required |
| LLC vesting often allowed | Keep the asset inside your business structure |
| Vacancy can affect terms | Compare lease-based and market-rent programs before choosing |
If you already know your numbers, send me the scenario and I will tell you what the programs on my panel would likely say.
How do lenders count rent on a property with no lease?
- The appraiser provides a market rent estimate, usually on a rent schedule form.
- Where a lease exists, many lenders compare it with market rent and use the lower number.
- For a property with an ADU, rent may be counted per unit if the space is permitted and finished.
With no tenant, the appraiser becomes your witness. They look at comparable rentals nearby and estimate what your property should rent for. That market rent number goes into the ratio.
Then the lender adds up the full payment: principal and interest, property taxes, insurance, and any HOA dues. Divide rent by payment and you have your DSCR. A ratio of 1.0 means rent exactly covers the payment. Many programs want to see 1.0 or higher, and stronger ratios can earn better pricing.
The calculator below lets you test your own numbers, including what happens with and without the ADU rent.
Vacant Property DSCR Calculator
An educational estimate, not an approval. Programs and minimum ratios vary by lender.
Does a new ADU change how my property is financed?
- It can add rent and value if it is permitted, complete, and has a certificate of occupancy.
- Some lenders treat a property with an ADU as a two-unit, which can change the program.
- Unpermitted or unfinished space generally cannot be counted and can stall the loan.
An accessory dwelling unit is a beautiful thing for an investor. It can double your rent roll on the same lot. But lenders need proof it is real: permits, final inspections, and a certificate of occupancy. If any of that is missing, the appraiser may not count the space at all.
Two practical points. First, the unit count can change the program. A single-family home with an ADU may be underwritten as two units, which opens some programs and closes others. Second, local zoning and rental rules differ by city and county, so confirm what is allowed before you underwrite your rent assumptions. Checking zoning before you underwrite is time well spent.
- Benefit: more rent and a higher appraised value. Feature behind it: a permitted, finished second unit.
- Benefit: a smoother appraisal. Feature behind it: clean permit and CO paperwork.
Not sure if your vacant property fits?
Send me the address, the unit count, and your estimated rent. I will tell you plainly what to expect.
Start My Scenario ReviewBook a Free CallWhat should I do before applying so the deal does not stall?
- Gather the certificate of occupancy, permits, entity documents, and an insurance quote.
- Get a realistic market rent for each unit from a local property manager.
- Decide whether to lease first or go on market rent, and compare both.
Most delays on vacant properties come from paperwork, not qualification. Use the checklist at the bottom of this article and tick items off as you collect them.
And be honest with yourself about the vacancy plan. If a tenant is two weeks away, a lease-based program may price better and it is worth waiting. If carrying costs are heavy or a seller is waiting, a market-rent program can get you moving. I would rather show you both side by side than guess.
Your Vacant Property Readiness Checklist
- Permits and a certificate of occupancy come first.
- Entity documents and insurance come second.
- A realistic rent estimate and vacancy plan come third.
Document Checklist
Tap each item as you collect it.
0 of 7 complete
Have most of these? Send them over for a free review.
Frequently Asked Questions
Can I get a DSCR loan on a vacant property?
Often yes. Many DSCR programs qualify a vacant property using the appraiser’s market rent estimate instead of a signed lease. Terms vary by lender, and refinances on vacant properties may have lower maximum loan-to-value limits or seasoning rules than leased ones.
What is a DSCR loan in plain English?
A DSCR loan is an investor mortgage that qualifies the property, not your personal income. The lender compares the property’s rent to its monthly payment, including principal, interest, taxes, insurance, and HOA dues. DSCR stands for debt service coverage ratio.
Does the rent on a new ADU count toward DSCR?
It can. If the ADU is permitted, finished, and has a certificate of occupancy, an appraiser may include its market rent, and some lenders treat the property as a two-unit. Lender treatment varies, so confirm before you count on it.
Do I need a lease to get a DSCR loan?
Not always. Some programs require a signed lease and others accept market rent from the appraisal, especially on purchases. If a lease exists, many lenders compare it to market rent and use the lower figure.
What DSCR do I need to qualify?
Many programs look for a ratio of 1.0 or higher, meaning rent covers the payment. Stronger ratios, often 1.2 or higher, can earn better pricing and leverage. Some programs allow a ratio below 1.0 with trade-offs such as a lower loan-to-value or a higher rate.
Will a vacant property get a lower maximum loan amount?
It can. Some lenders reduce the maximum loan-to-value on vacant cash-out refinances or require a minimum period of ownership first. Your broker can check current guidelines for your property.
Is it better to rent the unit before I apply?
Often it is worth comparing. A signed lease can open lease-based programs that sometimes price better. If waiting costs you a deal or carrying costs are high, a market-rent program may be the better trade.
What if my ADU was built without a permit?
That is a serious obstacle. Lenders and appraisers generally want permitted, finished space with a certificate of occupancy, and unpermitted work can stop a loan. Talk to your local building department about options before you apply.
Can I put the property in an LLC and still get a DSCR loan?
Yes, many DSCR lenders allow LLC vesting on investment properties, with entity documents and often a personal guarantee. Requirements vary, so share your structure up front.
Your finished project deserves a loan that fits
You already did the hard part. Let me help you pick the financing that matches it, with no pressure and no jargon.
Start My Scenario ReviewBook a Free Call