

Florida VA Loan Limits by County 2026: The Full vs. Partial Entitlement Truth Most Veterans Never Hear
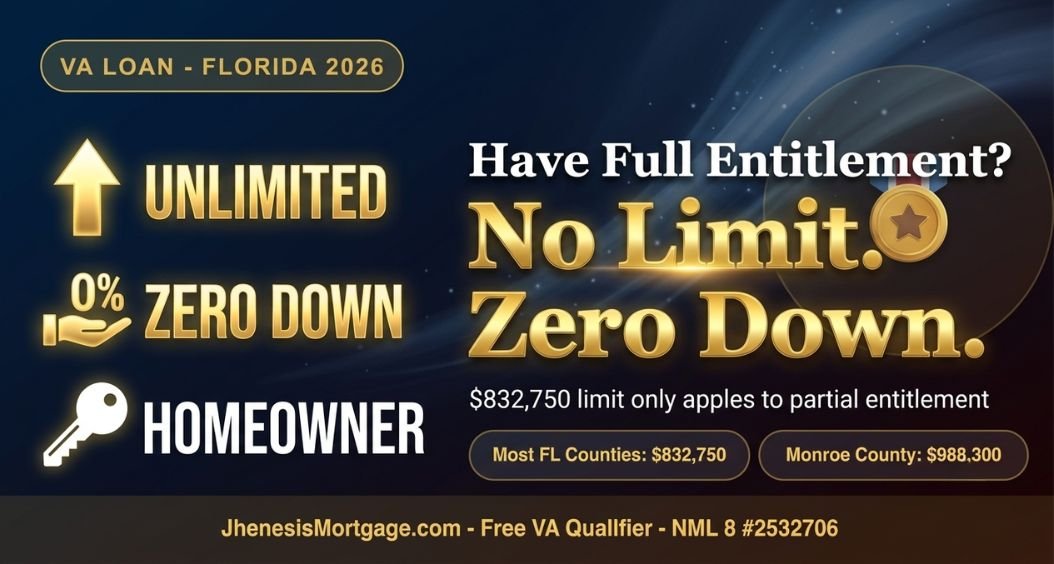
If you have full VA entitlement, there is no loan limit. You can buy a $1.5 million home in Florida with zero down. Here’s the complete breakdown — every county, every scenario.
Get My VA Loan Scenario Run Free →Let me start with the statement that changes everything for most Florida veterans: if you have full VA entitlement, there is no maximum loan amount and no down payment requirement. The “VA loan limit” that shows up in county tables? That only matters if you have partial entitlement — which means you currently have an active VA loan somewhere else, or you previously defaulted on one.
Most first-time VA buyers — and most buyers who have paid off their previous VA loan and had entitlement restored — are in the full entitlement category. The limit doesn’t apply to them. At all. Yet I regularly speak with veterans who think they can only borrow up to the “county limit” without a down payment. That misunderstanding has cost real people real money.
Let’s fix it right now.
Full Entitlement vs. Partial Entitlement — The Core Distinction
✅ Full Entitlement — No Loan Limit, Zero Down at Any Price
- First-time VA loan users
- Veterans who paid off a prior VA loan and had entitlement restored
- Veterans who sold their VA-financed home (and loan was paid in full at closing)
- Veterans whose prior VA loan was assumed by a qualified veteran who substituted entitlement
If this is you: no county limit applies. Zero down on a $300K or a $1.5M home.
⚠️ Partial Entitlement — County Limit Matters
- Veterans with an active VA loan on a different property
- Veterans whose prior VA loan was paid off but entitlement was NOT restored
- Veterans who had a prior VA loan foreclosure or short sale that reduced entitlement
If this is you: the county conforming limit determines your zero-down borrowing ceiling. A down payment can extend beyond that limit.
2026 VA Loan Limits by Florida County
These limits apply only to veterans with partial entitlement. They define the zero-down borrowing capacity. Veterans with partial entitlement CAN borrow above the county limit by making a down payment equal to 25% of the amount over the limit.
| Florida County | 2026 VA Loan Limit (1-unit) | Notes |
|---|---|---|
| Monroe County (Florida Keys) | $986,300 | Only high-cost FL county |
| ALL OTHER FLORIDA COUNTIES — Standard Baseline | ||
| Alachua (Gainesville) | $832,750 | Standard |
| Baker | $832,750 | |
| Bay (Panama City) | $832,750 | Standard |
| Brevard (Melbourne / Cocoa) | $832,750 | Standard |
| Broward (Fort Lauderdale) | $832,750 | Standard |
| Charlotte (Port Charlotte) | $832,750 | Standard |
| Citrus | $832,750 | Standard |
| Clay (Orange Park) | $832,750 | Standard |
| Collier (Naples) | $832,750 | Standard |
| Duval (Jacksonville) | $832,750 | Standard |
| Escambia (Pensacola) | $832,750 | Near NAS Pensacola |
| Hillsborough (Tampa) | $832,750 | Standard |
| Indian River (Vero Beach) | $832,750 | Standard |
| Lake (Clermont / Leesburg) | $832,750 | Standard |
| Lee (Fort Myers / Cape Coral) | $832,750 | Standard |
| Leon (Tallahassee) | $832,750 | Standard |
| Manatee (Bradenton / Sarasota) | $832,750 | Standard |
| Marion (Ocala) | $832,750 | Standard |
| Miami-Dade (Miami) | $832,750 | Standard despite high prices |
| Nassau (Fernandina Beach) | $832,750 | Standard |
| Okaloosa (Fort Walton Beach / Destin) | $832,750 | Near Eglin AFB |
| Orange (Orlando) | $832,750 | Standard |
| Osceola (Kissimmee) | $832,750 | Standard |
| Palm Beach | $832,750 | Standard |
| Pasco | $832,750 | Standard |
| Pinellas (St. Pete / Clearwater) | $832,750 | Standard |
| Polk (Lakeland / Winter Haven) | $832,750 | Standard |
| Sarasota | $832,750 | Standard |
| Seminole (Sanford) | $832,750 | Standard |
| St. Johns (St. Augustine) | $832,750 | Standard |
| St. Lucie (Port St. Lucie) | $832,750 | Standard |
| Volusia (Daytona / Deltona) | $832,750 | Standard |
| All remaining 33 FL counties | $832,750 | Standard baseline |
Source: FHFA 2026 conforming loan limits (effective January 1, 2026). VA loan limits match conforming limits by county for partial-entitlement borrowers. Full-entitlement veterans have no loan limit.
VA Loan Benefits Beyond the Limit — What Makes It the #1 Military Benefit
Zero Down Payment
Full-entitlement veterans buy with 0% down at any price — no PMI, no monthly mortgage insurance, ever.
Competitive Rates
VA loans consistently price at or below conventional rates — the government guaranty reduces lender risk, which reduces your rate.
No PMI
Conventional buyers pay PMI at less than 20% down — often $150–$400/month. VA loans have no PMI, ever, at any LTV.
Assumable Loan
VA loans can be assumed by future buyers — if you got a low rate, a future buyer can take it over, making your home easier to sell in a high-rate environment.
Unlimited Use
VA entitlement can be used and restored multiple times. You can use your VA benefit, sell your home, restore entitlement, and use it again on your next purchase.
Foreclosure Protection
VA loan servicers are required to make reasonable efforts to help veterans avoid foreclosure — additional protections beyond conventional loan servicers.
🎖️ Florida VA Loan Qualifier & Zero-Down Calculator
Enter your situation to see your estimated zero-down purchasing power and whether county limits affect you.
*VA loans also require residual income analysis (not shown here). Rate estimate uses 6.5% for illustration. Actual rate subject to credit, market conditions, and lender pricing. VA Funding Fee not included. Contact Jhenesis Mortgage NMLS #2532705 for a complete, personalized VA loan scenario.
5 VA Loan Myths That Florida Veterans Still Believe in 2026
Frequently Asked Questions
You Served. This Benefit Is Yours — Let’s Use It Right.
I specialize in VA loans for Florida veterans, active duty, and surviving spouses. Whether you’re using your benefit for the first time or the third, I’ll make sure your entitlement is structured correctly, your rate is competitive, and your offer is positioned to win. One call — let’s talk strategy.
Run My Free VA Loan Scenario →Stacy Ann Stephens | Mortgage Broker | NMLS #1933745 | Jhenesis Mortgage NMLS #2532705
407-630-9766 | stacyann@jhenesismortgage.com | JhenesisMortgage.com
VA loan limit data sourced from FHFA 2026 conforming loan limits and VA Loan Network (Jul 2026). Limits effective January 1, 2026. Full-entitlement veterans have no loan limit per VA guidelines. Not a commitment to lend. All loans subject to credit and income approval. Not all veterans qualify. Consult the VA or an approved VA lender for eligibility determination.