

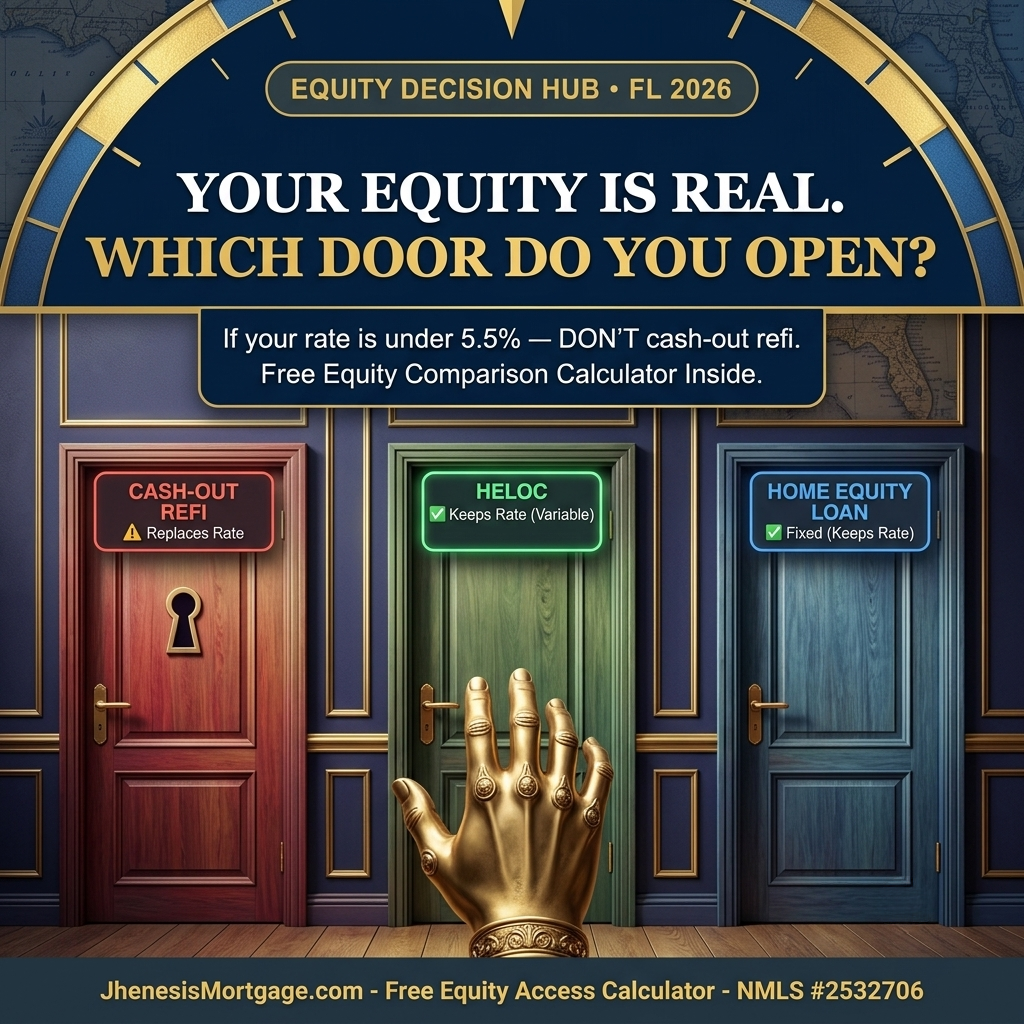
HELOC vs. Cash-Out Refi vs. Home Equity Loan in Florida 2026: Which One Is Right for You?
Florida homeowners are sitting on more equity than at any point in the last decade. The question is which door to open — and the wrong choice can cost you thousands over the life of the loan.
Get My Personalized Equity Strategy →If you’ve owned a Florida home for 3 or more years, there’s a good chance you’re sitting on significant equity. Median home prices in Florida remain near $376,000 — and even with some recent softening, the appreciation of the last few years has left most homeowners far ahead of where they started.
The question I’m getting more and more: “How do I access some of that equity — and which way is best?” The honest answer is that it depends entirely on why you need the money, how much you need, and whether disturbing your current mortgage rate makes sense.
Let me break down all three options clearly — no fluff, just the decision framework.
The Three Options — Side-by-Side
Cash-Out Refinance
- Replaces your entire existing mortgage with a new, larger loan
- You receive the difference in cash at closing
- One loan, one monthly payment
- Rate: today’s market rate (currently ~6.85–7.5% depending on credit/LTV)
- Closing costs: 2–5% of new loan amount (~$7,000–$16,000 typical)
- Loan amounts: up to 80% LTV on most conventional programs
- Best for: large lump sums when your current rate is already near market
HELOC (Home Equity Line of Credit)
- Revolving credit line secured by your home’s equity
- Draw what you need, when you need it (draw period: 5–10 years)
- Rate: variable, tied to Prime rate (currently ~8.5%)
- Interest-only payments during draw period
- Repayment period follows draw period (10–20 years)
- Closes costs: low ($500–$2,000 typical); some lenders waive
- Best for: ongoing projects, unpredictable costs, or when you need flexibility
Home Equity Loan
- Lump-sum second mortgage at a fixed rate
- Fixed payments for the life of the loan (5–30 years)
- Rate: fixed, currently ~8.0–9.5% depending on credit and LTV
- Predictable payment — no rate risk from Prime movement
- Closing costs: 2–4% of loan amount (lower than cash-out refi)
- Best for: known, one-time large expenses with a clear payoff plan
Which One Wins — Scenario by Scenario
A 20-minute conversation is genuinely all it takes. Tell me your current rate, your equity, and what you want the money for — and I’ll tell you which structure makes the most financial sense.
Get My Equity Strategy Consultation →
🏡 Florida Home Equity Access Calculator
Find out how much equity you can access — and compare the monthly payment across all three options.
*Estimates for comparison only. Cash-out refi replaces full first mortgage. HEL/HELOC are second liens — first mortgage payment not affected. HELOC rate shown as current draw period interest-only. Contact Jhenesis Mortgage NMLS #2532705 for personalized current rate quotes. Not a commitment to lend.
The Critical Question Most People Skip
Before choosing any equity access product, ask yourself: What is this money for, and does that purpose justify securing it against my home?
Home equity is a genuine asset. Using it for home improvements (particularly those that add value), debt consolidation that permanently changes spending behavior, or clear investment purposes (buying another property, funding a business) is a reasonable financial decision. Using it to fund lifestyle spending that won’t change is a different calculation — you’re converting unsecured consumer debt into secured mortgage debt, meaning your house is now collateral for that decision.
I’m not here to tell you what to do with your equity. But I am here to make sure the tool you choose fits the purpose — and that you understand the full picture before you close on anything.
Frequently Asked Questions
Your Equity Is a Tool. Let’s Make Sure You’re Using the Right One.
There’s no universal best answer here — it’s entirely about your situation, your current rate, what you need the money for, and how long you plan to keep the property. That’s a 20-minute conversation, not a Google search. Let’s have it.
Book My Free Equity Strategy Consultation →Stacy Ann Stephens | Mortgage Broker | NMLS #1933745 | Jhenesis Mortgage NMLS #2532705
407-630-9766 | stacyann@jhenesismortgage.com | JhenesisMortgage.com
Informational only. Not tax or financial advice. HELOC interest deductibility subject to IRS rules — consult a CPA. Not a commitment to lend. All loans subject to credit approval. Rate estimates are illustrative.