You Inherited a House. Now What? Keep It, Rent It, Sell It, or Buy Out Your Siblings
Grief and paperwork don’t mix well, but the decisions don’t wait. Here’s a clear-headed way to think through your options — and the financing that makes each one possible.
There’s rarely a good time to inherit a house. Whatever led to it, you’re now holding decisions that have real deadlines — insurance, property taxes, upkeep — layered on top of grief, probate, and possibly negotiating with siblings who don’t all want the same thing.
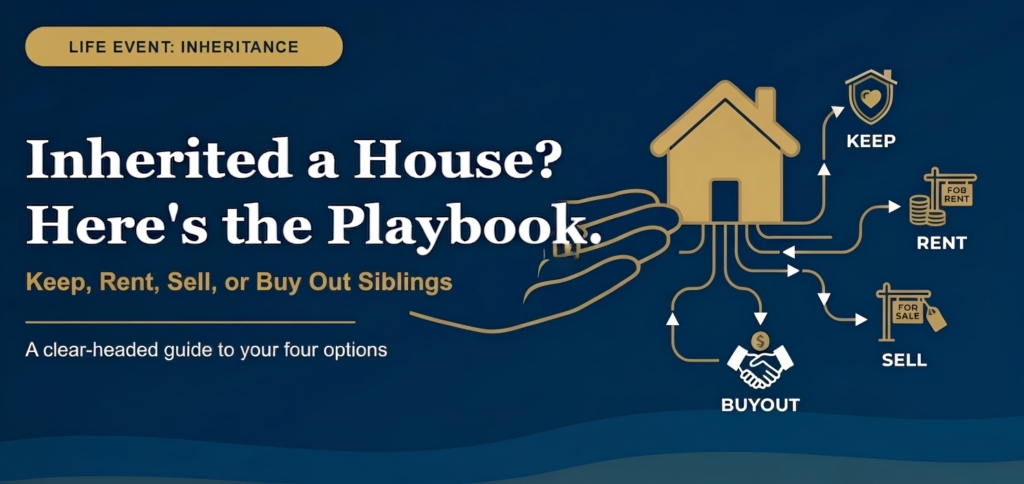
The good news: there are really only four paths from here, and each one has a clear financing route once you know which one fits your situation. The mistake we see most often isn’t picking the wrong path — it’s not deciding, and letting insurance lapse or taxes go unpaid while the family figures it out.
Let’s walk through the first-30-days protective steps, then the four paths, and what it actually takes — financially — to buy out a sibling if that’s the direction you’re headed.
Not sure which option fits your family’s situation?
Every inherited-property situation is different — the number of heirs, the mortgage balance (if any), whether everyone agrees. Let’s talk through the numbers before decisions get made under pressure.
Talk Through My OptionsFirst 30 Days: Protect the Asset Before You Decide Anything
Before you decide keep, rent, sell, or buyout, there are a handful of things that need attention regardless of which direction the family goes:
- Confirm homeowners insurance is active — a policy can lapse or become void if the named insured has passed and no one notifies the carrier. An uninsured, unoccupied home is a real risk.
- Keep property taxes and any existing mortgage current — even mid-probate. A tax deed sale or foreclosure doesn’t pause for family decisions.
- Establish who has legal authority to act — typically the personal representative or executor named in probate. Until that’s settled, decisions can stall.
- Get a date-of-death appraisal or valuation — this matters both for splitting things fairly among heirs and for tax purposes, since inherited property generally receives a “stepped-up” cost basis to fair market value at the date of death. That’s a conversation for your CPA, but it’s worth having early.
- Secure the property — change locks if appropriate, stop mail, winterize or otherwise protect it if it will sit vacant for any length of time.
Your Four Paths, Side by Side
| Path | What It Requires | Best When |
|---|---|---|
| Keep & Live In It | One heir buys out the others (see below) or all heirs agree to co-own and one occupies | One heir wants it as a primary residence and can qualify |
| Keep & Rent It Out | A DSCR loan qualifies on the property’s rental income rather than personal income — useful since heirs are often still settling their own finances | No one wants to live there, but the numbers work as a rental |
| Buy Out Co-Heirs | The remaining heir refinances (often cash-out) to pay the others their share | One heir wants sole ownership, others want cash, not co-ownership |
| Sell & Split Proceeds | List and sell, proceeds divided per the will or intestate succession law | No heir wants to keep it, or heirs can’t agree on any other path |
One note worth flagging early: when heirs disagree and no one buys the others out, “heirs’ property” can become vulnerable to a forced partition sale — where a court orders the property sold, sometimes below market value, because the co-owners can’t reach agreement. Getting ahead of the conversation, even an uncomfortable one, is almost always better than letting it default to a forced sale.
Co-Heir Buyout Calculator
Estimate the cost to buy out co-heirs and keep the home, assuming equal shares.
If Renting It Out Makes More Sense Than Selling
This is more common than people expect, especially when the home is paid off or close to it. A DSCR loan (Debt Service Coverage Ratio) qualifies primarily on what the property can rent for compared to its carrying costs — not on the heir’s personal tax returns or W-2 income. That matters here for a practical reason: heirs are often mid-transition themselves — settling an estate, sometimes between jobs, sometimes self-employed with income that doesn’t fit neatly into conventional underwriting. A DSCR cash-out refinance can let one heir take ownership, pull cash to pay out siblings, and hold the property as a rental, all financed against the deal itself rather than personal income documentation.
Working through this with siblings or other heirs?
We’ve helped families navigate exactly this — buyouts, DSCR rental conversions, and sales — without adding financial pressure on top of everything else. Let’s map out what your family’s numbers actually look like.
Get My Family’s NumbersInherited Property: Common Questions
Do I have to wait until probate is fully closed to refinance or sell?
It depends on your state’s probate process and whether the personal representative has authority to act — sometimes a sale or refinance can move forward during probate, sometimes it needs to wait for closing. This is worth confirming with the estate attorney handling probate, and we’re glad to coordinate directly with them on the financing side.
What if one sibling wants to keep the house and the others want cash?
This is exactly what a buyout refinance solves — the sibling keeping the home refinances (often with a cash-out component) to pay the others their share in one transaction, and everyone’s interest in the property is resolved at closing.
Can I qualify for a buyout refinance if my income doesn’t look great on paper?
If the property will be a rental after the buyout, a DSCR loan may let you qualify based on the property’s rental income rather than your personal income. If you’re moving in as your primary residence, we’ll look at your full income picture, including bank-statement or asset-based options if traditional tax-return underwriting doesn’t reflect your real cash flow.
What’s a stepped-up basis and why does it matter?
Inherited property generally receives a new cost basis equal to its fair market value at the date of death, which can significantly reduce capital gains tax if the property is later sold. This is a tax question for your CPA or estate attorney — we’ll flag it as something to ask about, but we don’t provide tax advice.
What happens if my siblings and I can’t agree on what to do with the house?
Left unresolved, disagreements over heirs’ property can end in a court-ordered partition sale, which isn’t always in anyone’s best financial interest. Getting real numbers on the table early — what a buyout would actually cost, what the home could rent for — often turns an emotional standoff into a solvable math problem.