Planning to Sell in a Year or Two? Why a HELOC Might Not Be Your Best Equity Option
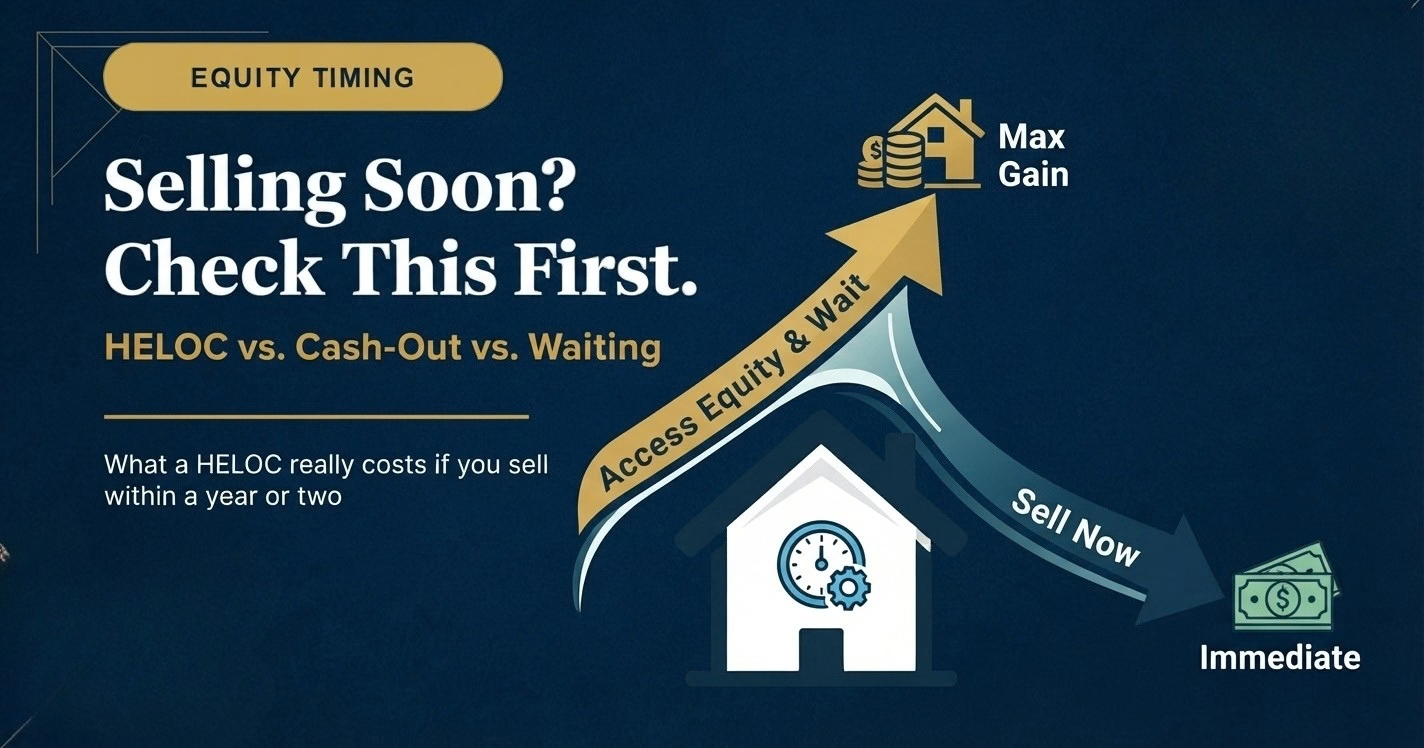
A HELOC solves today’s cash need. It doesn’t always solve it cheaply if you’re planning to sell before the ink even settles.
Needing to consolidate debt and planning to sell your home sometime in the next year or two are two separate decisions that often get tangled into one conversation — and that’s where things can go sideways financially.
A HELOC can feel like the obvious answer: access equity now, pay down higher-interest debt, keep moving. But a HELOC comes with its own fees, its own payment stacked on top of your existing mortgage, and a payoff requirement the moment you sell — regardless of how recently you opened it.
Before you open one, it’s worth running the real numbers against the alternatives, especially if a sale is realistically on your horizon.
Weighing a HELOC against an upcoming sale?
Before you open a HELOC, let’s run your real numbers against the alternatives — it only takes a few details to see which option actually costs less.
Compare My Equity OptionsThe HELOC Timing Trap
A HELOC isn’t a bad product. It’s a flexible line of credit against your home’s equity, and for many homeowners with no near-term plans to sell, it’s a smart way to access cash as needed. The trap is specifically about timing: a HELOC still has to be paid off in full when you sell your home, just like your first mortgage. If you open one, use it for a few months, and then sell, you’ve paid origination costs and possibly an annual fee for a tool you used only briefly.
Three Ways to Access Equity, Compared
| Option | How It Works | Best When |
|---|---|---|
| HELOC | A revolving line of credit against your equity, separate from your first mortgage | No near-term sale planned, want flexible ongoing access to funds |
| Cash-Out Refinance | Replaces your current mortgage with a new, larger one, with the difference paid to you in cash | You want one consolidated payment and plan to stay a while longer, or the new rate still works for your situation |
| Wait & Settle at Sale | Use sale proceeds directly to pay off debt once the home sells | A sale is realistically close, and the need isn’t urgent enough to justify new financing costs now |
What Actually Happens to a HELOC When You Sell
At closing, your title company pays off every lien against the property in order — first your primary mortgage, then your HELOC, then any other liens — out of the sale proceeds before you receive anything. If your HELOC balance plus your first mortgage balance is close to what the home is worth, you may walk away from the sale with far less cash than expected, or in a tight scenario, owe money to close.
Equity Access Timing Calculator
A simplified comparison of total cost between opening a HELOC now versus waiting until sale.
When It’s Smarter to Just Wait
If your need for cash isn’t urgent, and a sale is realistically less than a year or two away, running the math above often reveals that the fees and interest on a short-lived HELOC cost more than simply waiting and paying down debt from sale proceeds directly. This isn’t true in every case; a true emergency, a high-interest debt actively compounding against you, or a HELOC rate meaningfully lower than your other debts can tip the math the other way. The point isn’t that a HELOC is wrong, it’s that timing changes the answer, and it’s worth checking before you commit.
Not sure which option actually saves you more?
Bring me your numbers — your mortgage balance, your rate, your timeline to sell — and I’ll walk you through what each option really costs before you decide.
Schedule My Equity Timing ReviewHELOC vs. Cash-Out Refinance: Common Questions
Does a HELOC have to be paid off when I sell my home?
Yes — a HELOC is a lien against your property, and like your first mortgage, it must be paid off in full from the sale proceeds at closing, regardless of how recently it was opened.
Is a HELOC or a cash-out refinance better for debt consolidation?
It depends on your rate on each, your timeline, and whether you want one combined payment or a separate credit line. If a sale is on the near-term horizon, the comparison shifts further because both options carry a payoff-at-sale consideration.
What closing costs should I expect with either option?
A cash-out refinance typically carries closing costs similar to a standard refinance (often 2-5% of the loan amount). A HELOC generally has lower upfront costs but may carry an annual fee and, in some cases, early-closure fees if closed within a short window of opening.
Can I open a HELOC and still sell whenever I want?
Yes, nothing prevents you from selling after opening a HELOC — the consideration is purely financial: whether the fees and interest paid in the interim make sense given how soon you actually sell.
What if I need cash now but I’m not sure exactly when I’ll sell?
That uncertainty is exactly why running the numbers on a realistic range of timelines matters — the calculator above can be run with a shorter or longer estimate to see how sensitive the decision really is to your actual sale date.