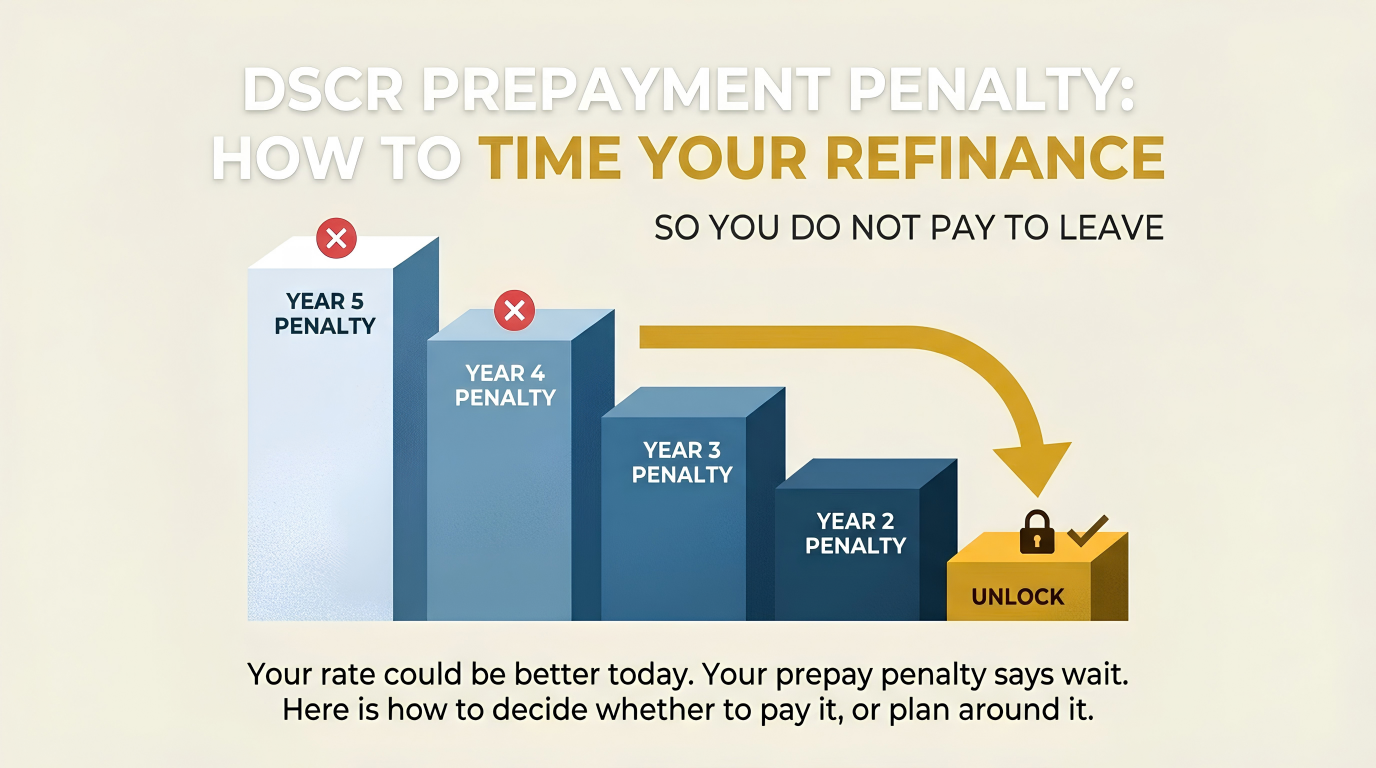
DSCR Prepayment Penalty: How to Time Your Refinance So You Do Not Pay to Leave
Your rate could be better today. Your prepay penalty says wait. Here is how to decide whether to pay it, or plan around it.
You took a DSCR loan to move fast on a deal, and it did its job. Now the rental has appreciated, or rates have shifted, or you want to pull cash out to buy the next one. Then you remember the prepayment penalty buried in your closing package.
The question is not whether the penalty exists. It is whether paying it still makes sense, or whether a few months of patience saves you a five-figure bill.
This is the math and the timing, laid out so you can decide with a calculator instead of a guess.
Sitting on a prepay clock?
Send me your note’s penalty schedule and your target. I will map the earliest date a refinance makes sense and what it would save.
Map My Refinance TimingHow Prepayment Penalties Are Usually Structured
Penalties vary by lender and note, so your own paperwork is the final word. These are the structures investors see most often:
| Structure | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
|---|---|---|---|---|---|
| 5-4-3-2-1 | 5% | 4% | 3% | 2% | 1% |
| 3-2-1 | 3% | 2% | 1% | 0% | 0% |
| Flat 3-year (example) | 3% | 3% | 3% | 0% | 0% |
| 6 months interest (example) | Six months of interest on the balance, for a set term | ||||
The percentage is typically applied to the unpaid balance, though some notes use the original loan amount. Some lenders also waive the penalty if you are paid off in the final few months of the term. Read your note for those exact words.
Three Questions to Ask Before You Refinance Early
- What is the penalty today, in dollars? Balance times the percentage for the year you are in.
- What do I gain each month? Payment saved, or the return the cash will earn on the next deal.
- How long until I break even? Penalty plus new closing costs, divided by the monthly gain.
If you plan to hold the property well past the break-even point, paying the penalty can be rational. If the break-even runs longer than you expect to keep the loan, waiting wins.
Prepay Penalty Break-Even Calculator
Assumes both loans are 30-year fixed on the same balance.
Smart Ways to Work Around the Penalty
- Wait for the next step-down. The calculator shows how many months until the percentage drops.
- Start the process early. Some investors time the closing for just after expiration. Ask about the lender’s rules on how early you can begin.
- Use a second lien instead. If the goal is cash, a closed-end second can leave the first loan, and its penalty, untouched.
- Negotiate the next loan’s penalty up front. A shorter or lower penalty is often available for a slightly higher rate. Pick based on how long you actually plan to hold.
Want the penalty structure that fits your hold period? Start a scenario review
Planning your next move?
Whether you are coming out of a penalty or about to enter one, I will help you choose terms that match how long you plan to hold.
Schedule My Investor Strategy CallDSCR Prepayment Penalty: Common Questions
What is a typical DSCR prepayment penalty?
Many DSCR loans carry a 3 to 5 year penalty, often a declining schedule like 5-4-3-2-1 or 3-2-1. Some lenders offer shorter or no-penalty options at a higher rate.
Is the penalty based on the balance or the original loan amount?
It depends on the note. Many use the unpaid balance. Check your loan documents for the exact wording.
Can I sell the property and avoid the penalty?
Usually not. Most prepayment penalties apply to any payoff within the period, including a sale, unless the note says otherwise.
Can I pay extra principal without triggering it?
Many notes allow a limited amount of extra principal each year. Others count any large paydown. Confirm with your servicer or your note.
Does a closed-end second lien trigger the penalty on my first loan?
Generally no, because the first mortgage stays in place. That is why a second lien is a common way to access equity during a penalty period.