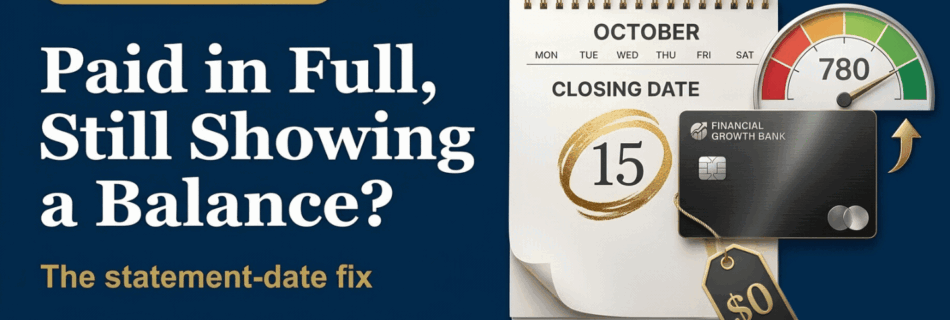
Why Your Credit Report Still Shows a Balance You Already Paid (And How to Fix It Before You Apply)

Paying your card in full does not always mean a $0 balance on your credit report. Learn how statement dates work, how lenders count the balance in your debt-to-income ratio, and when to pay before applying.
Can You Refinance a Property You Recently Listed for Sale? What the Listing Look-Back Means

If your property was recently on the market, many lenders pause cash-out until it has been delisted for a set period. Learn how the look-back works, what to document, and how to calculate your date.

Buying Your Family Member’s Home: How Down Payment Assistance and Gift of Equity Can Work Together

Buying a home from a relative at a below-market price is common, and it raises real underwriting questions most buyers don’t anticipate. Here’s how a gift of equity works, whether it can be combined with down payment assistance, and what the appraisal and paperwork need to show.

Planning to Sell in a Year or Two? Why a HELOC Might Not Be Your Best Equity Option

Accessing equity for debt consolidation makes sense, but the right tool depends heavily on your timeline. If you’re also planning to sell relatively soon, a HELOC’s fees and payoff mechanics can cost more than they save. Here’s a clear-eyed comparison, with a calculator to run your real numbers.

Denied for a New Construction Home Because You’re Self-Employed? Here’s the Fix

New construction underwriting runs on a strict timeline that conventional self-employed documentation often can’t keep up with. Here’s why self-employed buyers get denied near closing, how to protect your builder deposit, and the bank statement and P&L programs built for exactly this.

Can You Get a DSCR Loan on a New-Construction or Non-Warrantable Condo?

A great investment condo deal can die the moment a conventional lender flags the building non-warrantable. DSCR loans qualify on the property’s rental income and generally aren’t bound by the same agency condo rules. Here’s what still gets checked, and the red flags that can trip up even a DSCR approval.

The One-Time-Close Construction Loan: Build Your Home Without Two Closings or Two Rates

Building a home usually means two closings, two sets of costs, and a rate gamble while construction drags on. A one-time-close loan collapses all of that into a single closing with one rate locked up front. Here’s how draws, timelines, and qualifying actually work.