Can You Refinance a Property You Recently Listed for Sale? What the Listing Look-Back Means
A listing that did not sell can quietly block your cash-out. Here is how lenders view it, and how to plan around the look-back.
Plenty of investors list a property, get a few offers they do not love, and decide to hold it and refinance instead. It is a smart pivot, and it is also where a lot of files hit a wall.
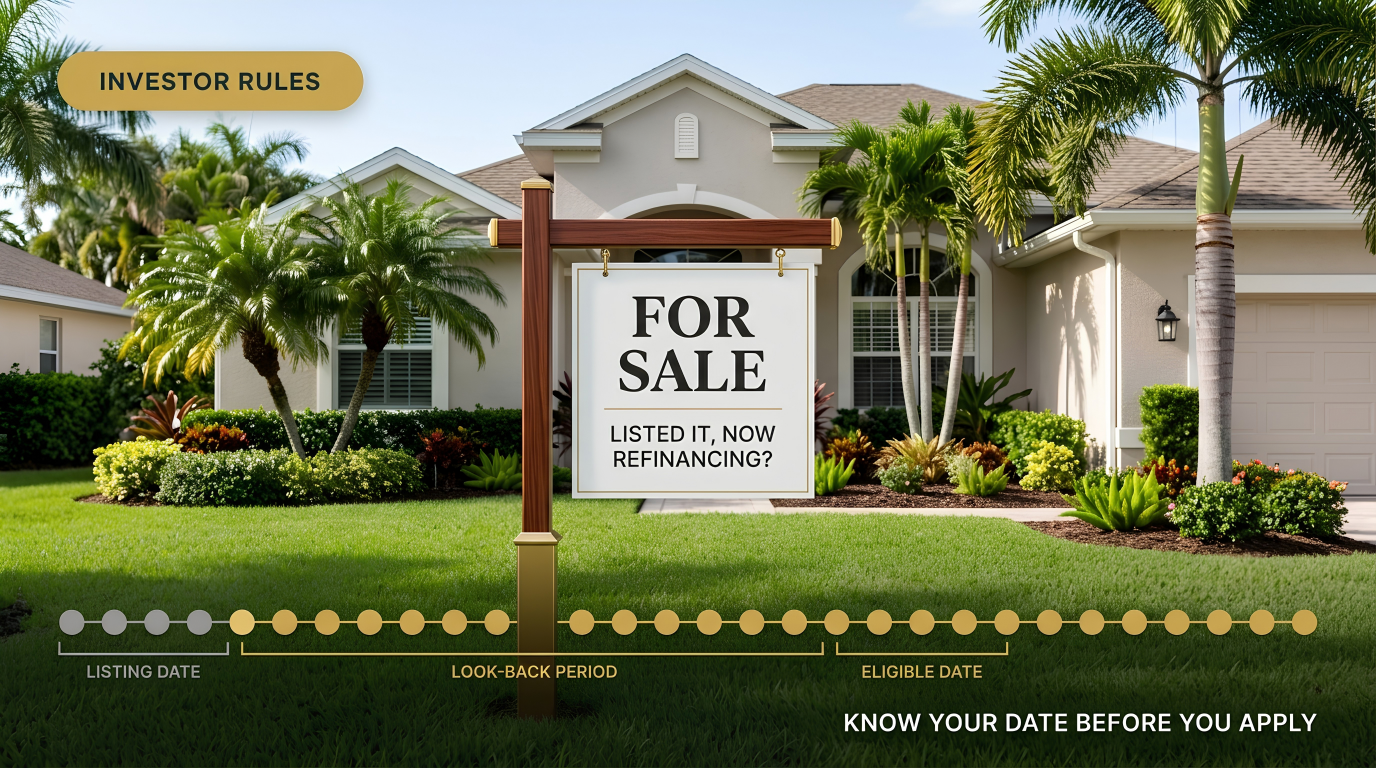
The reason is the listing look-back. Lenders want to know you actually intend to keep the property, and a recent listing says otherwise. Depending on the lender, you may have to wait, explain, or both.
Here is how the look-back works in practice, what lenders usually want to see, and how to figure out your earliest realistic date.
Took your property off the market?
Tell me when it was delisted and what you want to do next. I will check which lenders have the shortest look-back and what they need from you.
Check My Look-BackWhy Lenders Care About a Recent Listing
A cash-out refinance is a loan on a property you plan to keep. A listing is the opposite signal. If the property was on the market last month, the lender worries that you will sell soon, leaving them with a short-lived loan and, in some cases, a price that was set by an offer, not an appraisal.
So lenders add a rule. The names vary, but you will hear terms like listing look-back, delisting seasoning, or no active listing requirement.
The Three Rules People Confuse
| Rule | What it measures | Typical question |
|---|---|---|
| Property seasoning | How long you have owned the property | Have you owned it long enough, or is there a no-seasoning option? |
| Listing look-back | How long the property has been off the market | When was it delisted? |
| Max loan-to-value | How much you can borrow against value | What does the appraisal say? |
A property can clear one rule and fail another. A recently purchased property might qualify under a no-seasoning cash-out program and still be blocked because it was listed last month. Each rule has to be checked separately.
Not sure which rule applies to you? Start a scenario review
What Lenders Commonly Ask For
- Proof it is off the market. Often a listing history report showing the cancel or withdrawal date.
- A letter of explanation. Why you delisted, and why you now intend to hold it. Keep it factual and short.
- A signed lease or rent documentation. It supports the claim that the property is a rental.
- Appraisal support. The appraiser may be asked to comment on the prior listing price and any price reductions.
Note that a listing that expired or was cancelled is treated differently from one that was withdrawn or sold and fell through under some guidelines. Your exact status can change your options.
Look-Back Date and Cash-Out Estimate
Use the look-back your lender or program states. Estimates only.
Smart Moves If You Are Inside the Look-Back
- Get the delisting documented now. Save the cancellation date and any MLS history.
- Lease it. A signed lease at a market rent is the strongest proof of intent to hold.
- Compare lenders. Look-backs range from none to six months, so the lender you choose changes your date.
- Do not relist and delist repeatedly. A pattern of on-and-off listings hurts credibility.
- Consider a different structure. If you need cash sooner, a second lien or a bridge may have different rules.
Need cash from a property that was listed?
Tell me the dates and the goal. I will match you with the lender whose rules fit your timeline and tell you if it is smarter to wait.
Schedule My Investor CallRefinancing After a Listing: Common Questions
Can I do a cash-out refinance if my property is currently listed for sale?
Most lenders will not, and the listing generally has to be cancelled first. After that, a look-back period may apply depending on the lender.
How long is the typical listing look-back?
It varies. Some lenders have none beyond requiring the listing to be cancelled, while others require anywhere from 30 days to 6 months.
Does a rate-and-term refinance have the same restriction?
Often less strict, because no cash is being pulled out. Rules differ by lender, so ask before assuming.
Do I need a letter of explanation?
Frequently yes. Keep it short and factual: why you listed, why you took it off the market, and that you plan to hold it as a rental.
Does owning the property a short time affect this?
Separately, yes. Seasoning rules look at how long you have owned the property. Some programs offer cash-out with no seasoning, but the listing look-back is a different check.